
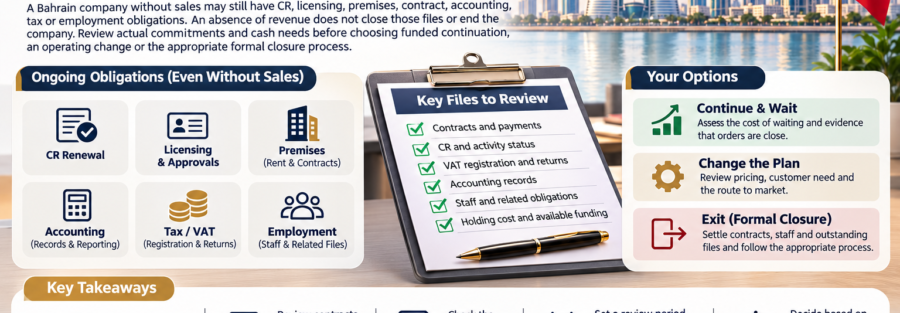
A Bahrain company without sales may still have CR, licensing, premises, contract, accounting, tax or employment obligations. An absence of revenue does not close those files or end the company. Review actual commitments and cash needs before choosing funded continuation, an operating change or the appropriate formal closure process.
Our financial management and accounting services with partners help review records and open files before you choose between continuation, an operating change and closure.
If the project has been delayed, make a clear decision about funding it, changing the plan or following the appropriate closure process. Leaving the file unattended is not the same as suspending its obligations.
No sales does not necessarily mean no transactions
Rent, subscriptions, fees, supplier payments and shareholder funding still need to be recorded even if the company has issued no sales invoice. Keep evidence for each transaction and distinguish funding from revenue, company expenditure from personal withdrawals, and one type of payment from another.
Organised records help establish what you have spent and how much longer you can afford to wait. They also assist the accountant if sales begin later or you decide to close the business.
Review existing contracts before stopping payments
A premises or software agreement does not automatically stop because sales have declined. Check its term, notice requirements, cancellation provisions and any outstanding amounts. Discuss a smaller service scope or lower cost with the other contracting party where appropriate.
If you want cheaper premises, check suitability for the activity and the necessary address updates. Do not replace one address on paper without addressing the company’s records and the original agreement.
Check the VAT position separately
If the company is VAT registered, do not assume that an absence of sales removes its filing requirements. Purchases, adjustments or other transactions may need to be considered. Deregistration has its own conditions and process rather than occurring automatically when selling stops.
An unregistered company also needs an assessment under the applicable registration rules. A lack of revenue alone does not decide every case, particularly where residence, supplies and expenses differ. The National Bureau for Revenue provides information on registration, deregistration and returns.
Choose between waiting, changing the plan and exiting
| Situation | What to assess | Practical Check |
|---|---|---|
| Orders expected soon | The cost of waiting and evidence that contracts are close | Sales plan and holding budget |
| Persistently weak sales | Pricing, customer need and the route to market | Review of the offer or sales channels |
| A long pause without a plan | Whether continuing recurring commitments is justified | Decision date and available funding |
| A decision to exit | Contracts, staff, outstanding files and the appropriate closure process | Settlement list and relevant authorities |
Set an internal review period with an observable outcome, such as reaching qualified customers or signing contracts. Avoid open-ended waiting while commitments consume the budget without progress.
Which Files Should You Review First?
List contracts, payments and expiry dates, then check the CR, activity status and existing registrations. Distinguish a company whose launch has been delayed from one that stopped after trading. The latter may have customers, suppliers, staff and earlier obligations requiring settlement.
Do not record owner funding as revenue to improve the apparent result, or ignore expenses because no sales occurred. Accurate records show the cost of waiting and the funding needed to continue. Keep evidence of contractual changes and settlements with counterparties.
Make the Continuation Decision Reviewable
Set a measurable commercial objective, an available budget and a decision date for the next phase. The objective might be qualified buyer discussions or testing a revised offer. If the outcome is not achieved, investigate the reason before automatically renewing commitments.
If closure is preferable, prepare a list of counterparties and administrative files to address. Cancelling an office arrangement or closing a bank account is insufficient by itself. The appropriate liquidation, removal or closure route depends on the entity and its obligations and requires a separate assessment.
For related decisions, see The Cost of Running a Bahrain Company After Formation, Preparing for Bahrain CR Renewal and Avoiding Delays and Managing a Bahrain Company After Formation.
Frequently asked questions
Can I ignore renewal because the company has sold nothing?
Do not rely on an absence of sales as a reason to ignore the registration. Review the requirements for your company and use the appropriate formal process if you decide not to continue.
Is a VAT return always a nil return when there are no sales?
Not necessarily. Purchases, adjustments and other transactions may affect it. Prepare the return from the correct records for the period rather than from sales figures alone.
Does closing the bank account close the company?
Closing the account alone does not deal with the CR, contracts or other obligations. Ending the company requires review of its structure and connected files and settlement of the relevant matters.
Does stopping sales automatically cancel VAT registration?
No. Review deregistration conditions and procedures, including any outstanding returns or adjustments, with the accountant and relevant authority.
Can I stop paying rent because the project is delayed?
Check the contract and any amendment agreed with the landlord. Review notice, termination and outstanding amounts before stopping payment.
Should I keep the company until a buyer appears?
Compare holding costs with an evidenced potential sale value while maintaining the files. An intention to sell does not suspend existing obligations.
About Zero Gravity Capital
Zero Gravity Capital has supported companies and investors with company formation and corporate services since 2016, with operations in Bahrain and Saudi Arabia and experience across multiple business sectors.
Zero Gravity Capital W.L.L. is licensed as a professional office by Bahrain’s Ministry of Industry and Commerce, under Commercial Registration No. 108831-1. See our accreditation and credentials.
Bahrain office: Office 665, Road 1808, Block 318, behind Exhibition Road, Manama, Kingdom of Bahrain.
Phone: +973 39775351. Email: info@zerogravitycapital.com.
Confirm current requirements through NBR VAT guidance and the authority responsible for your case. Requirements may change, and general information does not replace an assessment of your company’s circumstances.
Need to Review a Company With No Sales?
Send us:
- The activity, CR and licensing status.
- How long trading has stopped and existing contracts.
- Accounting, VAT and staffing position.
- Whether you are considering continuation, change or closure.
We can review the information, define the support scope and identify outstanding documents or requirements, including work needing specialist coordination or a separate budget.